AiFinLogix Weekly Report
From Oct 12–16, 2026, aggregate sector breadth weakened to 44.76% from 50.33%, and the number of sectors above 50% breadth slipped to five from six by the final session. The path was not one-way: breadth averaged 48.37% for the week, reached a high of 64.36% before fading, and ranged down to 35.00%, with one improving transition versus three deteriorating transitions across the observed snapshots. For next week, the forward outlook is defensive in distribution, with 0 constructive, 3 neutral, and 8 adverse sectors; no sector has a constructive next-week outlook.
Week in Review
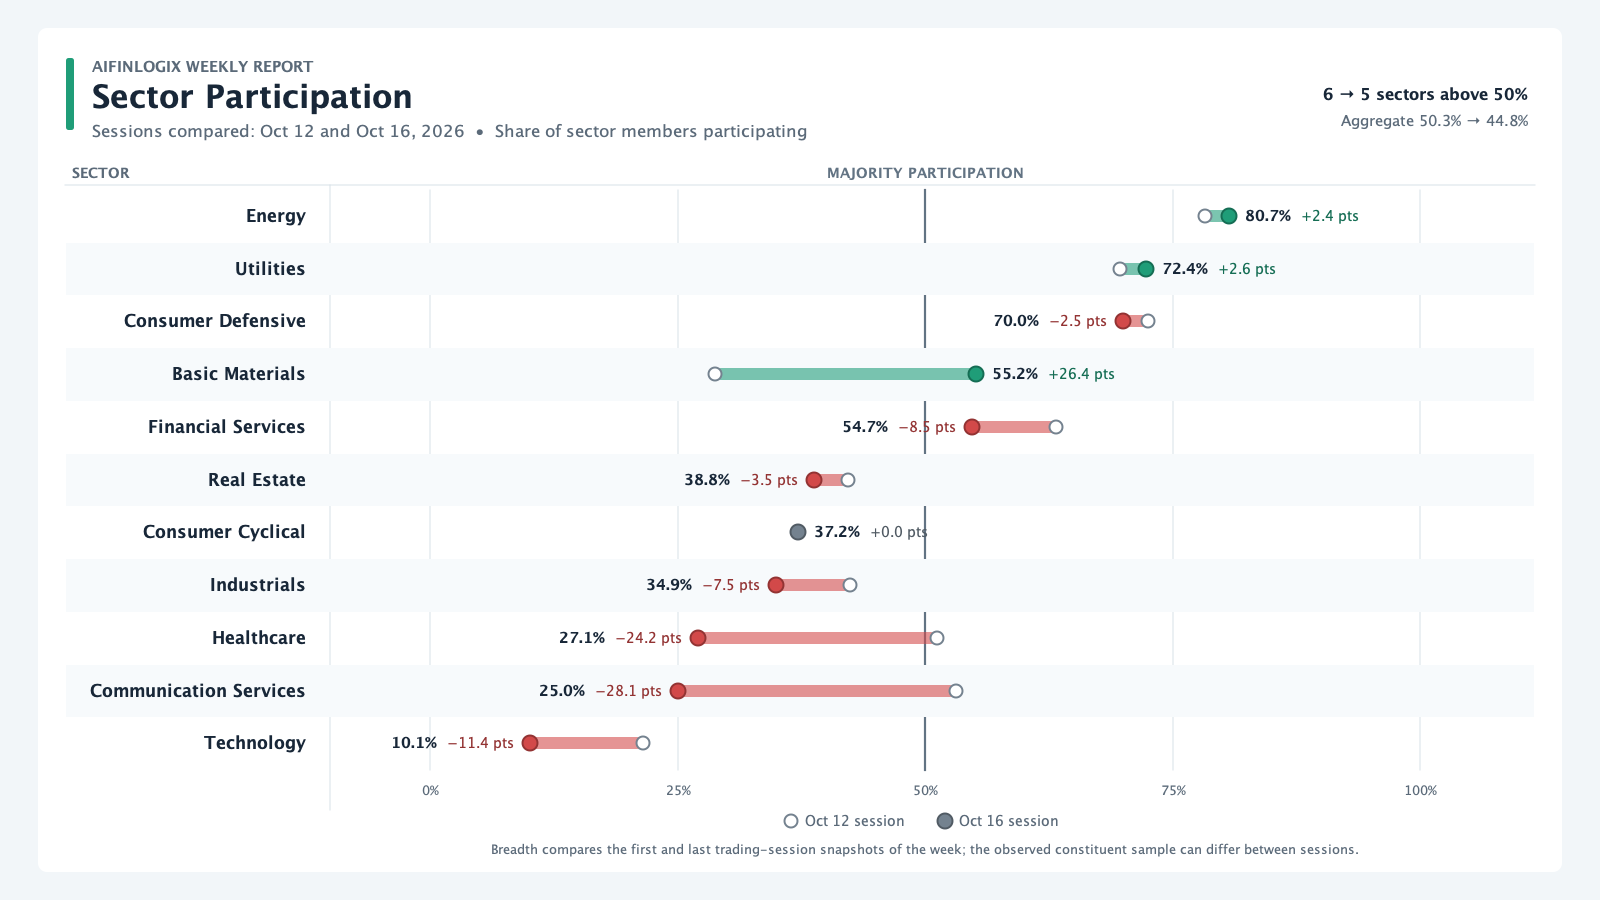
- Sector Breadth: Aggregate breadth fell 5.57 percentage points from 50.33% to 44.76%, while sectors above 50% breadth declined from six to five. Even so, the intra-week path was mixed rather than linear: the weekly average was 48.37%, the maximum reached 64.36% before the finish, and the minimum was 35.00%, with deterioration outnumbering improvement by three transitions to one.
- Participation: Participation softened across both measures. Aggregate equal-weight return moved from -0.0171% to -0.3956% across the start and end snapshots. The average sector weighted return moved from 0.2934% to -0.0873%.
- Improved: Basic Materials showed the clearest observed improvement, rising to rank 4 from rank 9 as breadth expanded 26.43 percentage points to 55.17% and the observed sector condition improved to constructive. Utilities advanced to rank 3 from rank 7 while remaining constructive, with breadth improving to 72.37% from 69.74%. Energy held rank 1 and strengthened further, with breadth rising to 80.72% from 78.31% and the observed sector condition moving from bullish to strongly bullish.
- Weakened: Communication Services deteriorated the most, falling to rank 10 from rank 3, while Healthcare also weakened, slipping to rank 7 from rank 5.
- Key Divergence: Energy finished the week at rank 1 with stronger breadth and a stronger observed sector condition, yet its forward sector outlook for next week is adverse with modest model directional confidence of 58.8%, underscoring that relative rank, observed condition, and forward outlook are separate measurements.
Last week’s outlook vs realized
Realized comparison unavailable.
Forward Sector Outlook
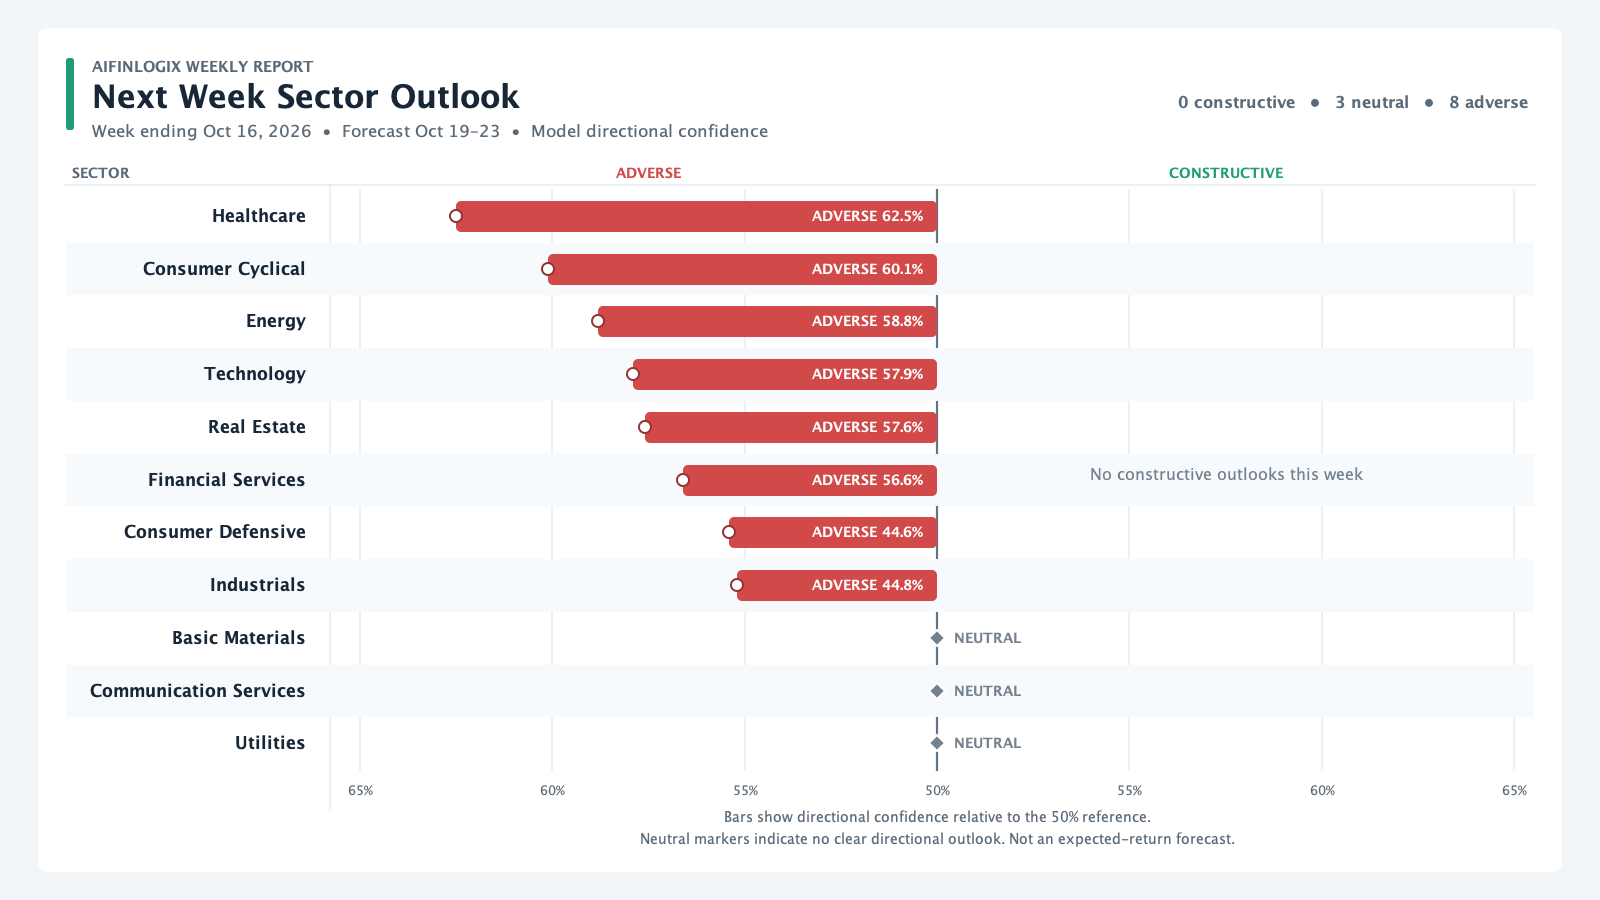
Next week (Oct 19–23, 2026): 0 constructive / 3 neutral / 8 adverse. No sector has a constructive next-week outlook.
- Sector View: The directional outlook is concentrated on the adverse side, while Basic Materials, Communication Services, and Utilities are neutral, meaning the model does not show a clear directional view for those sectors next week.
- Confidence Context: Reported scores are model directional confidence for the stated direction, not expected return magnitude. The reported adverse-sector scores range from 44.6% to 62.5%. Values near 50% indicate weak directional separation; these scores are not expected returns or guarantees. The model classifications are preserved independently of those scores.
Reading Next Week’s Daily Pulse
The weekly sector outlook is best used as a context layer for interpreting next week’s stock-specific BUY, WATCH, and AVOID classifications. A sector’s forward outlook can help frame whether a security-level signal is appearing within a more supportive, neutral, or adverse sector backdrop, but it does not mechanically override the security-level classification. In practice, the weekly view helps readers separate broad sector context from individual stock evidence rather than treating them as the same signal.
Weekly Bottom Line
The week ended with softer breadth and weaker participation after an intervening improvement, and the next-week model distribution remains skewed toward adverse rather than constructive outcomes. The most important reading is selectivity: some sectors improved on observed rank and breadth, but the forward outlook still argues for distinguishing current sector condition from the model’s next-week directional assessment when interpreting the coming week’s research.
Methodology and Limitations
The observations compare five persisted sector snapshots from October 12–16, 2026. The return figures above describe the start and end snapshots, not compounded weekly returns. Constituent observation counts vary, and source row update timestamps and historical freshness coverage are unavailable. The next-week outlook covers October 19–23, 2026; original forecast generation and feature-as-of timestamps are not established. Prior-issue publication is not yet reconciled, so no realized forecast grade is asserted. Model estimates are uncertain and losses are possible.
Disclaimer
AiFinLogix content is provided for informational and educational purposes only and does not constitute investment, financial, legal, or tax advice. Any market views, trade setups, entry zones, targets, stops, or risk parameters are general in nature and are not tailored to any individual’s objectives or circumstances. Trading and investing involve risk, including the possible loss of principal. Past performance is not indicative of future results. Readers should conduct their own due diligence and consult a qualified financial professional before making investment decisions.